

Welcome to The Silver Tsunami. Tuesday's midterms are projected to change who runs Congress beginning in January. They did not change the math on a $3 million plumbing business, but they could change the timeline, the financing, and the price. This week: what actually matters for Main Street buyers and sellers, a shutdown contingency clause for SBA-financed deals plus a free checklist for subscribers, Weil's wind-down and what it teaches about key-person revenue, a $15.3 billion AI holdco take-private (and the Grok ad Elon Musk just reposted), the Red Baron guy, and the deal side of Bill Ackman's story that the replies asked for.

~ SMBASH 2027: Tickets Go On Sale Black Friday
ETA Twitter goes offline. SMBash 2027, the national gathering of the ETA community, is April 21-22, 2027 at The Rayleigh Underground in Irving, Texas. Tickets go on sale Black Friday, November 27. Set a reminder now, because the room will not wait for you.
Sponsorships are open. If your brand serves searchers, operators, or capital partners, this is the room. Details at smbash.com/sponsors.
Full disclosure: Kevin and Sam Rosati are co-owners of SMBash.
~ THE WAVE: Washington Changed Hands. Payroll Is Still Due Friday.
On Wednesday morning, Eric posted this: "Democrats just flipped BOTH chambers of Congress. Trump still controls the White House. Everyone is looking at Wall Street. We're thinking about the 65-year-old guy who owns a $3 million plumbing business and wants to retire."

What happened. CBS News and other networks projected that Democrats will control both the House and the Senate. Final margins were still being counted on Wednesday. The terms of the new Congress begin January 3, 2027. Until then, the current Congress remains in office.
We are not going to tell you whether that is good news. We are M&A lawyers. What we can tell you is where a change in Washington actually shows up in a deal file. Five places.
1. SBA lending and the shutdown clock. The last federal shutdown ran 43 days. SBA estimated it was unable to deliver $5.3 billion in 7(a) and 504 financing to roughly 10,000 small businesses during that stretch. Divided government does not make the next shutdown inevitable. It does raise the stakes of every funding deadline. During the 2025 shutdown, SBA halted new 7(a) and 504 approvals, but the closing risk depends on where your loan sits when a shutdown begins. A 7(a) loan that already has an SBA loan number may still be disbursed; a loan that still needs SBA approval can be stuck until processing resumes. If your deal is SBA-financed, know exactly what SBA action remains outstanding before the next funding deadline. (This week's Clause is about exactly that.)

Illustration
2. Taxes. Under P.L. 119-21, commonly known as the One Big Beautiful Bill Act, the 20% qualified business income deduction under Section 199A is permanent, and qualified property acquired and placed in service after January 19, 2025 generally qualifies for 100% bonus depreciation, subject to the statute's rules and elections. In tax law, permanent means no scheduled expiration date. A later Congress can still change either provision, but ordinary legislation needs both chambers and a presidential signature, or enough votes to override a veto. For a buyer modeling an asset deal, the step-up and depreciation assumptions in your model are current law today. Underwrite current law, and stress-test the downside.
3. Tariffs. A new Congress can hold hearings, increase oversight, and pursue legislation affecting trade policy. But a change in congressional control does not by itself repeal existing tariffs. For a target that imports inputs, tariff exposure is a diligence item right now: who the suppliers are, where the goods come from, and whether customer contracts allow the business to pass cost increases through.
4. Labor and healthcare. A change in congressional control does not change either overnight. New legislation would need to pass Congress and become law, while agencies and courts can also move labor and healthcare rules under existing law. But for a 15-employee business, these are not abstractions. They are line items. A buyer underwriting that business should know what it pays for health coverage today, how its people are classified, and what happens to margin if either number moves.

5. Valuations. This is the one that hits retirement. In BizBuySell's Q3 2026 Insight Report, 2,132 businesses sold, flat from Q2 and down 7% from a year earlier. The median sale price rose 17% to $350,000. Buyer confidence slipped to 49 and seller confidence to 47. And 27% of owners planning to sell said they are considering selling sooner because of current conditions. BizBuySell president Bob House put it this way: "Confidence has softened, but buyers haven't left the market. They're simply becoming more selective." BizBuySell's closed-deal data is voluntarily reported, so treat it as a market indicator, not a census. For millions of owners, the business is the retirement plan. Tighter financing, higher costs, or nervous buyers all show up in one place: the price.

Illustration
What we would actually do this week.
Under LOI with SBA financing? Build shutdown contingency into the timeline now: outside dates, extension rights, and who carries rate-lock or deposit costs if the agency stops processing.
Modeling a deal? Use current tax law. Do not price in a rescue or a disaster.
Thinking about selling? Uncertainty discounts fall hardest on businesses that depend on the owner. Fix that before you go to market. (See the Ledger.)

Illustration
Eric ended his post with a line we keep coming back to: "There's a guy in Ohio trying to buy a machine shop, keep 20 people employed, and make payroll on Friday." Wall Street gets the attention. Main Street lives with the consequences.
~ THE CLAUSE
One provision a week, from people who draft them for a living. (Catch up on past Clauses: anti-assignment, indemnification, commercially reasonable efforts, and the financial statements rep.)
This week: the outside date, and how an SBA-financed deal can address a shutdown before one happens.

What it is. The outside date (also called the termination date or drop-dead date) is the date after which a party with the applicable termination right may terminate the agreement if the closing conditions have not been satisfied or waived. Agreements commonly bar a party from using that right when its own breach caused the failure to close. It keeps a deal from hanging open indefinitely.
Why it matters now. A lapse in appropriations can freeze new SBA loan approvals and the issuance of SBA loan numbers. A loan that already has its SBA loan number may be in a different position, so the shutdown risk depends on where the financing sits in the process. If a required SBA action cannot happen, the clock in your purchase agreement keeps running unless the contract says otherwise. A buyer who did everything right can run out of time on a schedule neither party controls, and a seller can end up with a business off the market and no closing.

Illustration
What to negotiate.
A shutdown extension. An automatic extension if closing is delayed because the SBA has suspended loan processing, tied to the date processing resumes plus a set number of days.
A hard backstop. For the seller, the extension needs a ceiling. An extension with no end date is just an option the buyer holds for free.
Deposit treatment. Say plainly whether the earnest money is refundable if financing fails for a reason outside the buyer's control.
A financing contingency that names the loan. "Subject to financing" is weaker than a contingency tied to the specific SBA loan, lender, and material terms.
Interim operating covenants. If closing slips 60 days, the seller should keep running the business in the ordinary course, and the buyer should know what "ordinary course" means.
Other clocks. Lease assignments, landlord consents, license transfers, and rate locks often have their own deadlines. Line them up with the outside date.
Illustrative language: "If the Closing has not occurred on or before the Outside Date to the extent caused by a lapse in federal appropriations that suspends or materially delays the issuance of an SBA loan number, guaranty, authorization, or other SBA action required for the Financing, the Outside Date shall automatically be extended until the date that is [30] days after the applicable SBA processing resumes, but in no event later than [date]."
That is a starting point, not a form. The right version depends on your lender, your lease, and your deal.
~ FREE THIS WEEK: The SBA Shutdown Contingency Checklist
Every subscriber gets this one free, right here in the email. Sixteen things to address now to reduce the risk that a lapse in appropriations derails an SBA-financed closing. Print it, put it in the deal file, and send it to the buyer or seller you are working with.

Step 1: In the LOI
Realistic outside date. Build in SBA processing time, not just lender time.
Say "shutdown" out loud. Flag that a lapse in appropriations can extend the timeline.
Deposit terms. Address whether the deposit is refundable if the specified SBA financing becomes unavailable despite the buyer's timely compliance with its financing obligations.
Step 2: In the purchase agreement
Shutdown extension. Automatic, tied to the date SBA processing resumes plus a set number of days.
Hard backstop. A final date so the extension cannot run forever.
Interim covenants. Ordinary course, no new debt, no unusual distributions, no key-employee changes.
Seller cooperation. A duty to deliver what the lender and SBA need, on time.
Step 3: Before a funding deadline
Ask your lender today. Does the loan have its SBA loan number? What SBA action is still outstanding?
Calendar it. Put the next federal funding deadline next to your target closing date.
Rate lock. When does it expire, and who pays to extend it?
Every other clock. Landlord consent, lease assignment, license transfers, franchisor approval, insurance binders.
Step 4: If a shutdown hits
Notice mechanics. Follow the agreement's notice provisions. Do not assume a phone call satisfies them.
Sign the amendment. Document any extension in a signed amendment, not an email thread.
Keep moving. Finish diligence and closing documents so you can close soon after processing resumes.
Talk to the other side. A delay you explain is a problem to solve. A delay you hide becomes a trust problem.
Know someone with an SBA deal in the pipeline? Forward them this issue. They can subscribe free here and get the next one.

Illustration
~ THE LEDGER: When the Rainmakers Walk
Last week, Weil, Gotshal & Manges, one of Wall Street's best-known law firms, announced that its management committee had recommended an orderly wind-down, subject to a partnership vote. The firm generated more than $2 billion in revenue last year, according to JD Journal's summary of the reporting. A wave of partner departures was a major catalyst, including corporate chair Michael Aiello and five others to Cravath, a private equity partner to Paul, Weiss, and two London M&A partners to Sullivan & Cromwell, alongside leadership uncertainty and merger talks with Willkie Farr & Gallagher that did not produce a deal. Weil intends to wind down outside bankruptcy, with restructuring advisers in place, and associates and staff were reportedly told they would be paid for 90 days.

Illustration
The morning the news broke, Eric wrote that he would be extremely nervous if he woke up as an associate at a prestigious firm with a big salary, a family, debt, little visibility into what was really happening, and limited exit options to sustain that lifestyle. A lot of people agreed.
Kevin's read. Kevin saw the buyer lesson:
"While it may not seem it on its face, this story is very relevant for small business buyers. You must pay attention to your revenue sources, especially when they're tied to people. If you buy a business doing $8M in revenue but $7.5M of that revenue is coming through the personal relationships of the owner/seller, the risk that that revenue walks out the door after closing is exponentially higher than if $7.5M of that revenue was coming from other channels that remain with the business. 6 months ago Weil was at the top of the world. Today they're headed for bankruptcy because too many of their rainmakers walked out the door."
(Factual note: Kevin posted before Weil clarified its planned path. The firm says it intends an orderly wind-down outside bankruptcy, subject to a partnership vote. The portability point does not depend on bankruptcy.)

The seller version. Eric made the same point from the other side of the table on Monday. Buyers do not pay for what it took to build your business. They pay for what they will get from it after closing: clean financials, a management layer, revenue that keeps coming, and systems and people who keep doing the work after the seller is gone. Those businesses draw bidding wars. The ones held together by the owner and his cell phone often do not sell at all, or sell at a discount. That lines up with this week's Main Street Deals, where we dug into why bigger businesses are selling above asking while smaller ones sell below.
What to ask in diligence.
What share of revenue comes from customers whose main relationship is the owner? Who else at the company knows those customers by name?
Do key customer contracts require consent to assignment in an asset deal, or contain change-of-control or termination rights in an equity deal?
Is there a real transition plan, including a consulting agreement, a retention-based earnout or holdback where appropriate, and enforceable non-compete and non-solicit covenants where applicable law permits?
If the answer to the first question is "most of it," you are not buying a business yet. You are buying a relationship that has not agreed to come with you.
~ THE SPLIT
Same question to Grok, ChatGPT, and Claude: With divided government starting in January 2027, should a small business owner who planned to sell in the next two years sell sooner? One word, then three sentences. This week, they actually split. The answers below are reproduced verbatim; their political and policy predictions belong to the models, not to us.

GROK: YES. "Divided government typically produces legislative gridlock that slows financing availability, raises compliance costs, and injects uncertainty into valuation multiples for small-business exits. With Democrats projected to control both chambers, they are likely to advance higher capital-gains and estate-tax proposals that, even if vetoed, will chill buyer confidence and lender appetite over the next 18–24 months. Owners who already intend to exit should therefore compress their timeline now, while current tax rates and deal momentum remain intact, rather than risk a narrower buyer pool after January 2027."
CHATGPT: NO. "A Democratic Congress with President Trump in the White House likely means legislative gridlock, making major federal capital gains tax increases difficult to enact. For most small business owners, changes in EBITDA, buyer demand, interest rates, and valuation multiples will matter far more than election results. Start preparing to sell now, but accelerate only if market conditions or business fundamentals justify it, not because of political uncertainty."
CLAUDE: NO. "Selling on a political calendar is usually a mistake, because any tax change still has to pass both chambers and get a presidential signature, and nobody can reliably time that. What actually moves your price is inside the business: how much depends on you, how clean the books are, and whether the revenue keeps coming after you leave. If the business is ready, sell when the right buyer shows up; if it is not, a rushed sale will likely cost you more than any policy change."
Our take: Do not sell on a political calendar. The YES case depends on policy forecasts that remain speculative. The NO answers focus on what a seller can actually control: earnings, transferability, financing, buyer demand, and readiness. If you are two years out, spend the next six months on the Ledger diligence questions above, not on a fire sale.
~ THE FINE PRINT: The AI Holdco Is Buying Home Security
On October 29, ADT agreed to be taken private by Thrive Holdings for $10 a share in cash. Reported terms: about $7.6 billion in equity value, about $15.3 billion in enterprise value including debt, a premium of roughly 46%, and a 30-day go-shop (Axios, ADT's 8-K). The deal is signed, not closed, and remains subject to shareholder and regulatory approvals. Thrive Holdings is led by Josh Kushner. OpenAI is an investor in and strategic partner to Thrive Holdings; under their 2025 partnership, OpenAI said its teams would work inside Thrive Holdings companies, starting with accounting and IT services, to build a repeatable model for AI-driven operations. ADT's announcement says Thrive Holdings will bring its own engineering capabilities to ADT. No specific OpenAI deployment at ADT has been announced.

Why this matters on Main Street. The thesis is simple. Buy an essential service business with trusted relationships, then use AI to change what it costs to deliver the service. Searchers and holdco builders have been pitched that thesis for two years, mostly in accounting, IT services, and insurance brokerage. Now a holding company built around that thesis is applying it in a $15.3 billion enterprise-value transaction. Expect more capital chasing the same idea at every size, including yours.
Case in point. On Wednesday morning, Eric posted a video ad he spotted running on another platform: a creator walking through how to use Grok to buy a local plumbing company. Elon Musk reposted it, and it passed 100,000 views within hours. Buying a home services business has officially gone mainstream. That means more buyers, more competition for the good businesses, and more people learning what diligence is the hard way. Watch it yourself:
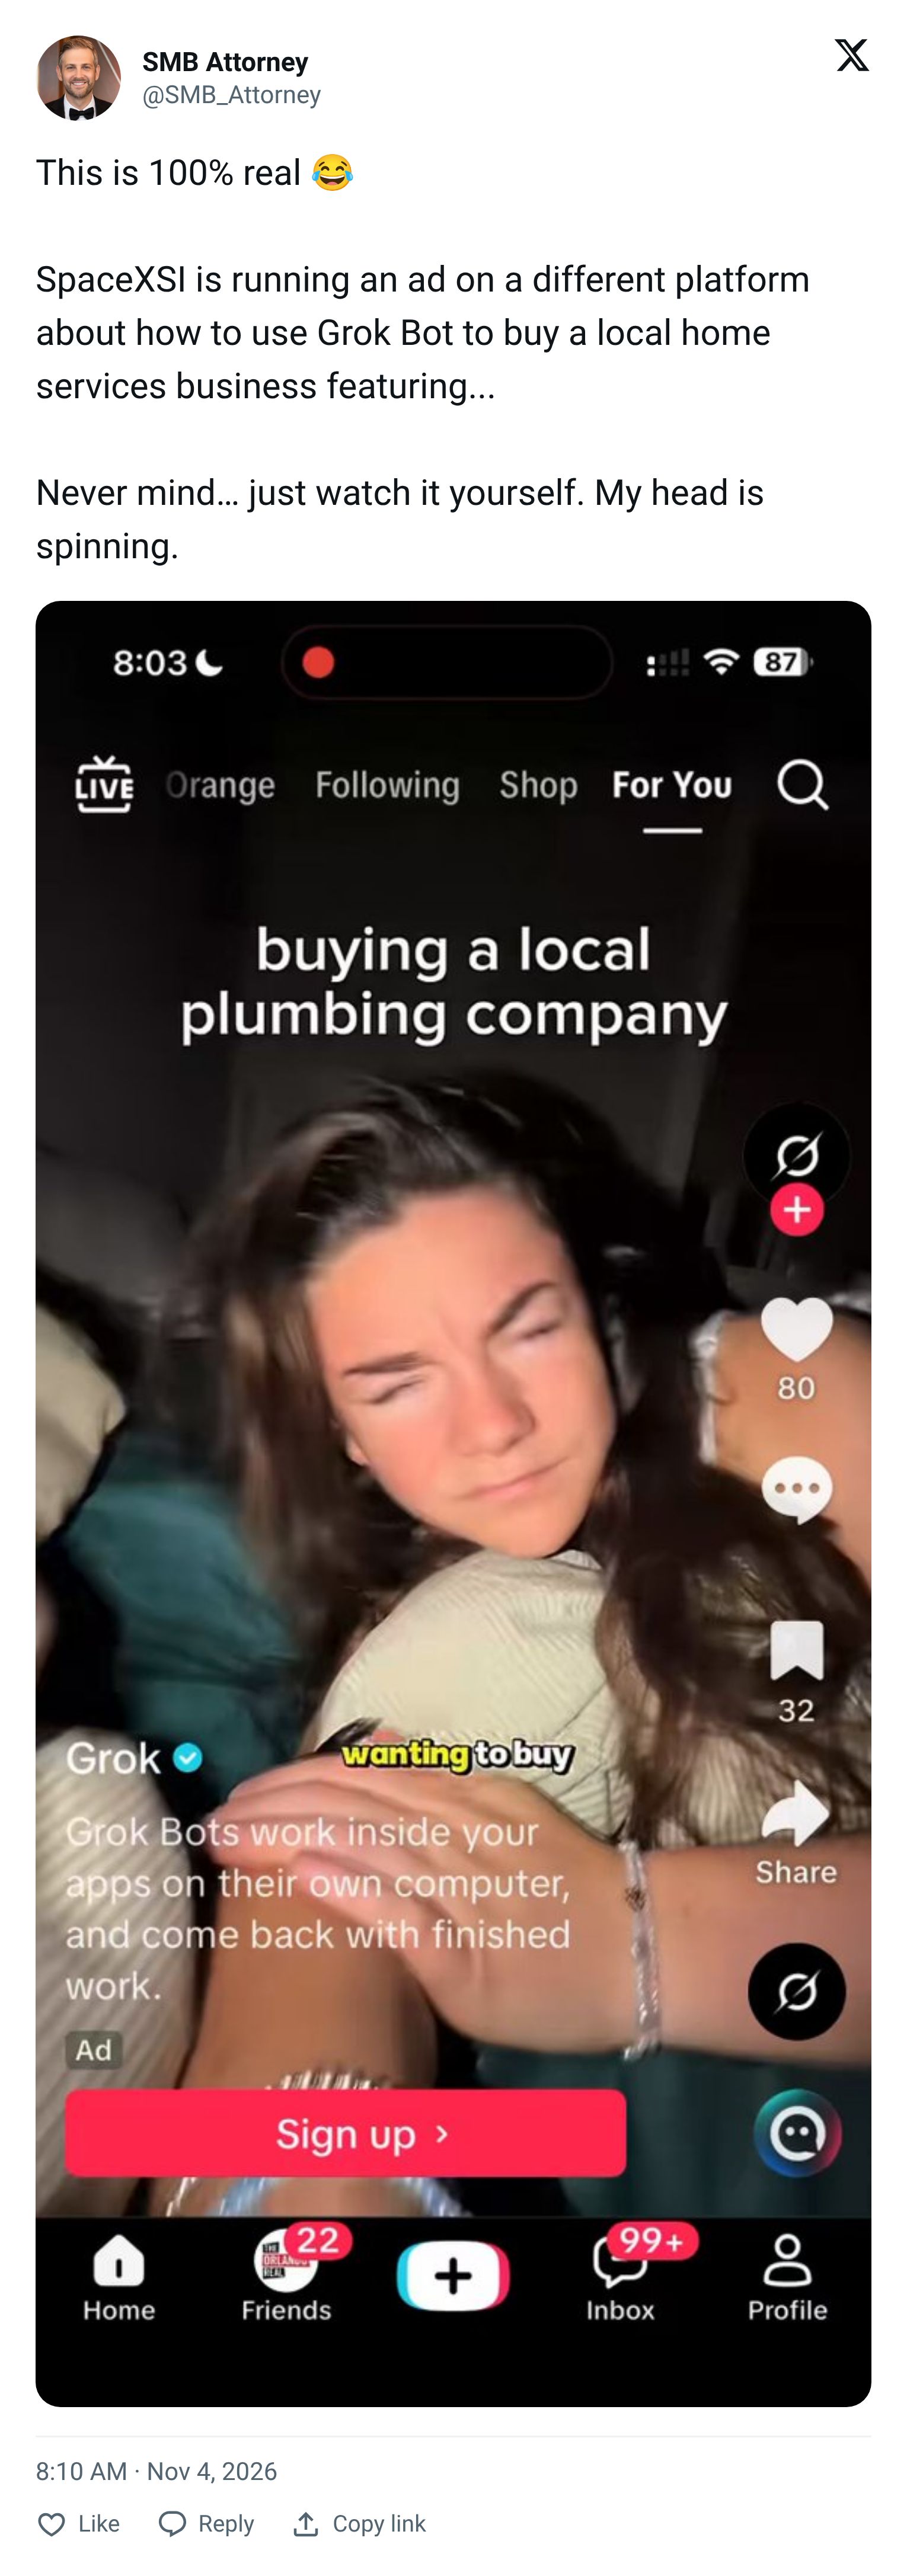
Two terms worth knowing. A go-shop lets the seller actively solicit better offers for a set period after signing, usually with a lower breakup fee if a better bid wins. The premium is a reminder that the market price and the price a buyer with a plan will pay are two different numbers. Every seller of a Main Street business is asking the same question: who is the buyer with a plan?

Illustration
Eric's post on the deal walked through the backstory around the buyer, and it is worth a read. We will stick to the deal terms here.
~ UNDERTOW: The Red Baron Guy
You have probably seen the video. Two pranksters approached Walt Zerod, a Red Baron worker stocking a grocery freezer in Michigan, asked him for the time, then played a fake Apple Pay sound to make it look like they had stolen money from his phone. His reaction, from a father of four working long days, was raw and real. The internet turned on the pranksters, and their Instagram account was deactivated (Daily Wire).

Illustration
Then the story got better. Luke Oakenshield, a military veteran, tracked Walt down and started a GoFundMe that raised more than $680,000 (The Post Millennial). A separate fundraiser organized for Luke by a friend says that Luke is currently homeless and living in his car (Dexerto). By the weekend, Eric noted that it had passed $30,000.
Eric publicly offered to help Walt if he ever needed legal support, then declared Red Baron Pizza Day and sent his Pizza Friday money to Walt's fundraiser.

The business lesson. Red Baron did not launch a campaign. It posted that "employee of the month nominations are closed," and a spokesperson said the company checked on Walt and that he remains a valued team member. That is the whole playbook. Acquired goodwill can sit on a balance sheet. In real life, it is how your company treats the person stocking the freezer when a camera is pointed at him.
The legal footnote. A grocery store is private property even when it is open to the public. The owner can generally set reasonable rules about filming and ask someone who will not comply to leave. State recording-consent laws can also matter when audio is captured. If you run a retail or service business, make sure your managers know the filming policy and when they can ask someone to stop or leave.
~ INTERESTING PEOPLE: Bill Ackman, the Deal Side
Eric's "Be Bill Ackman" thread drew a huge response this week, and the replies asked for more. So here is the promised deal side of the story. Three deals, three lessons.

Illustration
1. The earnout he sued Carl Icahn over. In the early 2000s, Ackman's Gotham Partners sold its stake in Hallwood Realty to Icahn at $80 a share. The deal included price protection: if Icahn sold within three years, they would split any profit above a 10% return. In 2004, Hallwood merged at $137 a share. Ackman said his share was about $4.5 million. Icahn did not pay. Ackman sued and won, and with interest he collected nearly $9 million. Icahn later called that kind of clause "schmuck insurance." The lesson for anyone signing an earnout or a price-protection clause: the interest and fee-shifting provisions can determine whether a disputed payment is economically worth pursuing.
2. Herbalife. In December 2012, Pershing Square disclosed a roughly $1 billion short position in Herbalife and argued the company was a pyramid scheme. Herbalife denied that characterization. Icahn took the other side, eventually became Herbalife's largest shareholder, and the two fought it out live on CNBC. Ackman exited the position in early 2018 (CNBC), and Icahn later said he had made about $1 billion on his Herbalife investment (CNN). The lesson: being confident in a thesis is not the same as controlling the timeline, and a short has no ceiling on the downside.

3. The $4 billion SPAC that gave it all back. In 2020, Pershing Square Tontine Holdings became the largest SPAC ever. Its plan to buy 10% of Universal Music Group from Vivendi fell apart after the SEC raised questions about whether the structure satisfied NYSE rules, talks with others went nowhere, and in July 2022 Ackman wound it down and returned about $4 billion to investors (Fortune). The lesson every searcher eventually learns: raising the money is not the deal. A structure the regulators or the counterparty will not accept does not close, no matter how much capital is behind it.
This week, Ackman compared today's market to a casino. Coming from a man who has been on both ends of billion-dollar bets, that is worth hearing.
~ THE TICKER: 27%

The share of owners planning to sell who told BizBuySell they are considering selling sooner than planned because of current conditions (Q3 2026 Insight Report). If more sellers move up their timelines at the same moment buyers get more selective, the businesses with clean books and a real team will get the bids. Everyone else gets the discount.

Illustration
~ RIPTIDE
Who's advising on Anthropic's IPO. Anthropic filed its registration statement on October 26. Wilson Sonsini is company counsel, Freshfields represents the underwriters led by Goldman Sachs and Morgan Stanley, and Cravath, Cleary Gottlieb, and Orrick have governance and compensation roles (Bar & Bench). Eric asked the obvious question: "Why don't they just use Claude?" Kevin had the better one: "Can you imagine the stress these law firms are under knowing every misplaced comma is going to be spotted by the client's AI platform? I wonder if that means they're billing more or less hours to ensuring things are 100% correct?"

Illustration
Save for the future? Elon Musk posted that "Saving money for the distant future is pointless with the advent of super intelligent abundance." Eric pushed back: why assume any future abundance would be shared broadly? Our vote: keep saving.
Off the balance sheet. The Kobeissi Letter tallied a record $3.3 trillion in future spending commitments disclosed by Alphabet, Meta, Microsoft, Amazon, and Oracle, mostly data centers, equipment, and leases (Axios explains why those numbers sit outside the balance sheet). Kevin translated it for buyers: "Sometimes the biggest liabilities never show up on the balance sheet. Important to remember when diligence a business to buy. QOE only tells a part of the story. Things like contractual liabilities are sometimes where the traps lie if you don't know what you're looking for!" (Accounting note: off-balance-sheet does not mean nonexistent. These are contractual commitments disclosed in filings that may not yet qualify as recognized liabilities.)
Who pays when it goes wrong. Hackers stole $6.3 billion from Binance in a heist analysts tied to North Korea, and Binance said it would cover the losses with its own funds (Reuters via The Daily Record). Kevin's take: "Binance did it exactly right, stating that it's using its own funds for the recovery effort, not customer funds. That said, when things get expensive, even if the customer doesn't pay directly, they end up paying indirectly."
Free, then gated. Reddit says it plans to move toward a primarily logged-in experience, starting with tests in select markets (Dexerto). Eric called it a classic move: make it free and accessible to all, then gatekeep it once people are hooked.

~ LISTEN: MAIN STREET DEALS
New this week: How to Differentiate Yourself as a Business Buyer. Bigger businesses are selling above asking, and smaller ones are selling below. We dig into the latest numbers, what that gap says about where the pricing power actually sits right now, and how a buyer stands out when the best businesses draw a crowd.

Listen on YouTube, Spotify, or Apple Podcasts.

Illustration
Know someone buying or selling a business? Forward them this email, or send them to ridethesilvertsunami.com/subscribe. It is free, every Thursday.
See you next week.
Eric and Kevin